
DSCR Loans in Conroe, TX for Rental Property Investors
TEXAS PREMIER MORTGAGE • CONROE INVESTMENT PROPERTY FINANCING
Put 20 years of Mortgage Experience behind your Next Investment Property.
Texas Premier Mortgage helps real estate investors purchase and refinance rental properties in Conroe, Texas, using DSCR financing. These loans qualify primarily through the property's rental income instead of personal employment income, making them an option for business owners, self-employed borrowers and investors building a rental portfolio.
Led by Steve Head, Owner and Top Rated Mortgage Broker, our team helps you compare the details that matter: down payment, monthly housing payment, cash needed to close, reserves and prepayment terms. Whether you're evaluating your first rental or your next acquisition, we start with your property and your goals.
Discuss Your Property: 281-204-8030
How a DSCR Loan Works
DSCR stands for Debt Service Coverage Ratio. For many residential investment property programs, it compares the lender's qualifying monthly rent with the property's monthly principal, interest, property taxes, insurance and association dues, often called PITIA.
DSCR = Qualifying monthly rental income ÷ Monthly PITIA
If qualifying rent is $2,500 and PITIA is $2,000, the DSCR is 1.25. That means qualifying rent equals 125% of the housing payment.
Illustrative calculation only.
Personal tax returns, W-2s and paystubs generally aren't used to establish qualifying income on these programs. Credit, assets, reserves, property eligibility and other underwriting requirements still apply. Our guide to DSCR loans without traditional income documentation explains this approach.
Looking for the Best DSCR Mortgage Broker in Conroe?
The best mortgage relationship gives you more than a number on a rate quote. It gives you someone who understands the transaction, explains your choices and helps you identify financing issues before they disrupt your plans.
Steve Head brings 20 years of mortgage experience to Texas Premier Mortgage. Based in The Woodlands and serving Conroe and investors throughout Texas, Steve combines personal attention with access to multiple lending options.
#1 Mortgage Broker in Texas
- Financing built around your priorities. We ask whether preserving cash, reducing the payment or maintaining flexibility matters most.
- Meaningful comparisons. We explain how points, down payment, reserves and prepayment terms change the overall loan structure.
- Clear communication. You know what documentation is needed and what comes next, with regular loan updates.
- Experienced transaction management. We help coordinate financing requirements with the appraisal, title work and closing timeline.
Learn more about Steve Head's experience with Texas DSCR financing and how we help investors.
A Conroe Rental Property Deserves an Address-Specific Review
Two properties with the same purchase amount can have very different monthly expenses. Before choosing a loan for a home in Conroe, Willis, Montgomery, Magnolia or the Lake Conroe area, review the details of that particular address.
- Property taxes: Use an appropriate investment-property estimate. A seller's exemptions or a new construction bill reflecting only land may not represent your future tax obligation.
- Insurance: Obtain a rental-property insurance quote early and include applicable flood coverage.
- Association dues and rental restrictions: Confirm the community permits your intended rental use and account for required dues.
- Rental support: Compare similar properties and distinguish asking rents from supported lease or appraisal data.
- Operating cushion: Budget for turnover, vacancy, maintenance and larger repairs in addition to the mortgage payment.
A long-term rental and a short-term rental near Lake Conroe may require different income documentation and program review. Discuss your intended use before committing to a financing strategy.
Making the Numbers Work When Interest Rates Are Higher
When financing payments rise, the value of a careful comparison rises with them. The question is whether the property's income, your available cash and the loan terms fit your investment plan.
| Decision | What we help you compare |
|---|---|
| Down payment | How a larger investment affects the loan balance and payment, while leaving enough cash for reserves and repairs. |
| Points versus cash retained | Whether an upfront amount for a lower rate makes sense over your expected holding period. |
| Prepayment terms | Whether the loan's payoff provisions fit a possible sale or refinance. |
| Purchase or refinance | How the proposed payment and cash requirements compare with your current position and goals. |
We evaluate the proposed loan using today's terms. A future refinance may become an option, but your purchase decision should not depend on a promised rate reduction or guaranteed appreciation.
When comparing the best DSCR lender for your investment, look at the complete structure and the guidance you receive along the way.
DSCR Financing for Purchases, Refinances and LLC Ownership
Purchase your next rental property
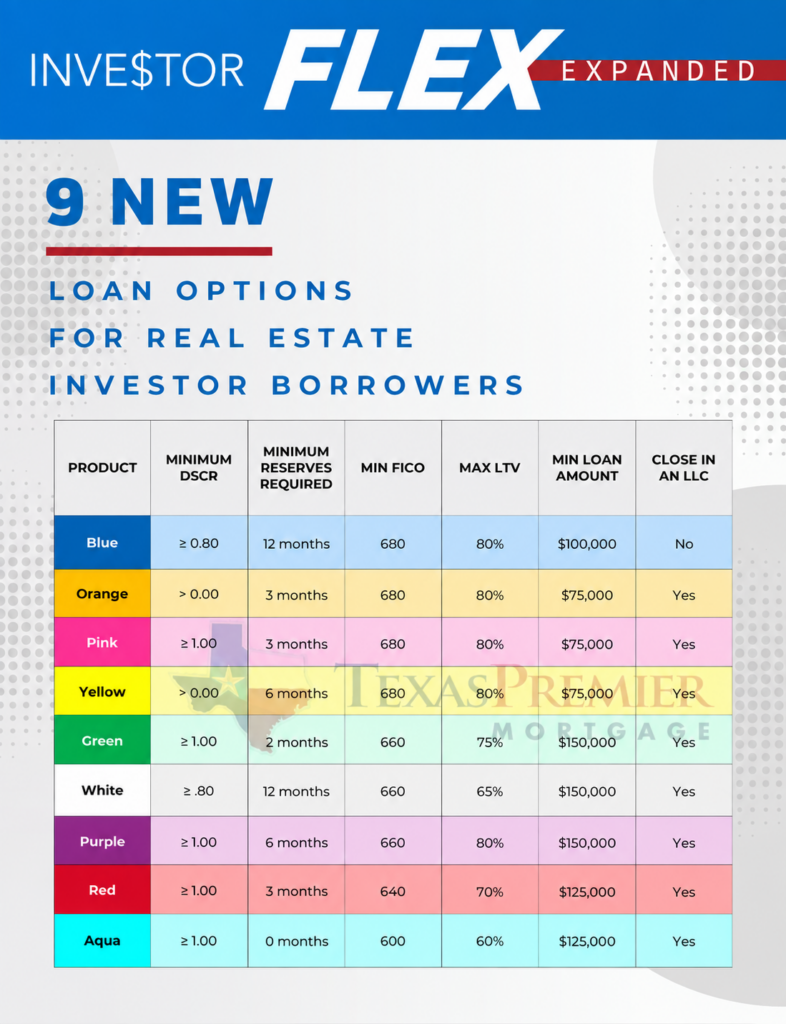
Our Investor Flex options include financing for eligible single-family rental homes, duplexes, triplexes and fourplexes. We review the property, rental income, credit profile and available funds to identify suitable options. Explore our Investor Flex DSCR financing options.
Refinance an investment property
A DSCR refinance may help you change an existing loan structure or access available equity through a cash-out transaction. We compare the proposed payment, closing amounts and any existing prepayment obligation before you decide. Cash-out eligibility depends on equity, rental income and the selected program.
Finance through an eligible LLC
LLC ownership is available on eligible DSCR programs. The lender must review the entity structure and required documents, and a personal guaranty may be required. Discuss ownership early so the financing and title arrangements can be coordinated before closing.
Plan for portfolio growth
DSCR financing can provide an alternative to personal-income qualification as you add rentals. Financed-property limits and reserve requirements vary by program. Our overview of DSCR mortgage loans for investors covers how this approach can fit a broader rental-property strategy.
Down Payment and Gift Fund Options
Depending on eligibility, we can review options with 20%, 25% or 30% down. The right amount depends on the property, credit, rental coverage and how much liquidity you want to retain.
For eligible gift-fund programs described in our current guide:
- 25% down: No minimum borrower contribution is required; eligible gift funds may cover the required investment.
- 20% down: The borrower contributes at least 5% of the purchase amount from their own funds.
- Less than 20% down: Gift funds are not permitted under those guidelines.
These provisions are program-specific. Donor eligibility, documentation and reserve requirements must also be reviewed. Read our DSCR gift fund guide and discuss the proposed gift with us before transferring money.
Conroe DSCR Loan Questions
Can I qualify without showing personal income?
DSCR programs generally use the property's qualifying rent instead of employment income. This can help self-employed investors and business owners whose tax returns don't fit traditional qualification. Credit and asset documentation are still part of the review.
Does the property need an existing tenant?
No. An eligible vacant property may qualify using appraiser-supported market rent. For a leased property, the lender reviews the lease and appraisal under its rental-income rules. An owner's projected rent alone does not establish qualifying income.
What if the DSCR is below 1.00?
Some programs accommodate lower rental coverage, with different requirements or rate pricing. We can review available options and whether a different down payment improves the structure. Qualification does not mean the property will generate positive net cash flow.
Can a first-time investor use a DSCR loan?
Yes. Depending on the program, credit, reserves and ownership history. First-time investor and first-time homebuyer requirements can differ, so tell us about your current housing situation when we review your scenario.
Can I use a DSCR loan for a home I plan to live in?
No. These DSCR options are for non-owner-occupied investment properties. If you intend to live in the home, we can discuss an appropriate owner-occupied loan instead.
Are short-term rentals eligible?
Eligible programs permit short-term rentals. The property, rental restrictions and acceptable income documentation need review. Financing eligibility does not replace checking local and association rules for your intended use.
What determines my DSCR interest rate?
The overall market conditions have a huge impact. Pricing can depend on credit score, loan-to-value ratio, rental coverage, loan amount, property type, transaction purpose, points and prepayment terms. A property-specific comparison is more useful than an advertised rate without those details.
Can I finance properties outside Conroe?
Yes. Texas Premier Mortgage serves investors throughout Texas, including other local areas: The Woodlands, Spring, Magnolia, Montgomery, Willis and the greater Houston area. Visit our Texas DSCR mortgage loan overview for more information.
Review Your Next Investment Property
Have a property in mind? Start with the address, purchase amount or estimated value, expected monthly rent and planned down payment. For a refinance, include the approximate mortgage balance and your goal.
Steve Head and Texas Premier Mortgage will help you compare financing options and identify the next step.
For more information about DSCR loans, their benefits and loan options and how it may apply to you, please contact us direct or submit the "Quick Quote" form on this page.
Which matters most for your next property: preserving cash, lowering the monthly payment or keeping flexibility for a future sale?


